Most companies budget weeks for an exit and end up managing it for over a year. That gap is not a filing error. It is the predictable result of underestimating what a foreign subsidiary actually requires before a registrar will agree it no longer exists.
Tax authorities, creditor notice periods, and payroll wind-down obligations do not move on your schedule, and in several jurisdictions, they cannot be accelerated at any price.
For finance and legal teams managing a market exit, restructuring, or portfolio consolidation, the question is rarely "Can we dissolve this entity?"
It is "How long will this entity remain a liability on our books, and what does that cost us in the meantime?"
Here is what the timeline actually looks like across the jurisdictions where companies exit most often, and what determines whether you land at the fast end or the slow end.
Let’s get into this blog!
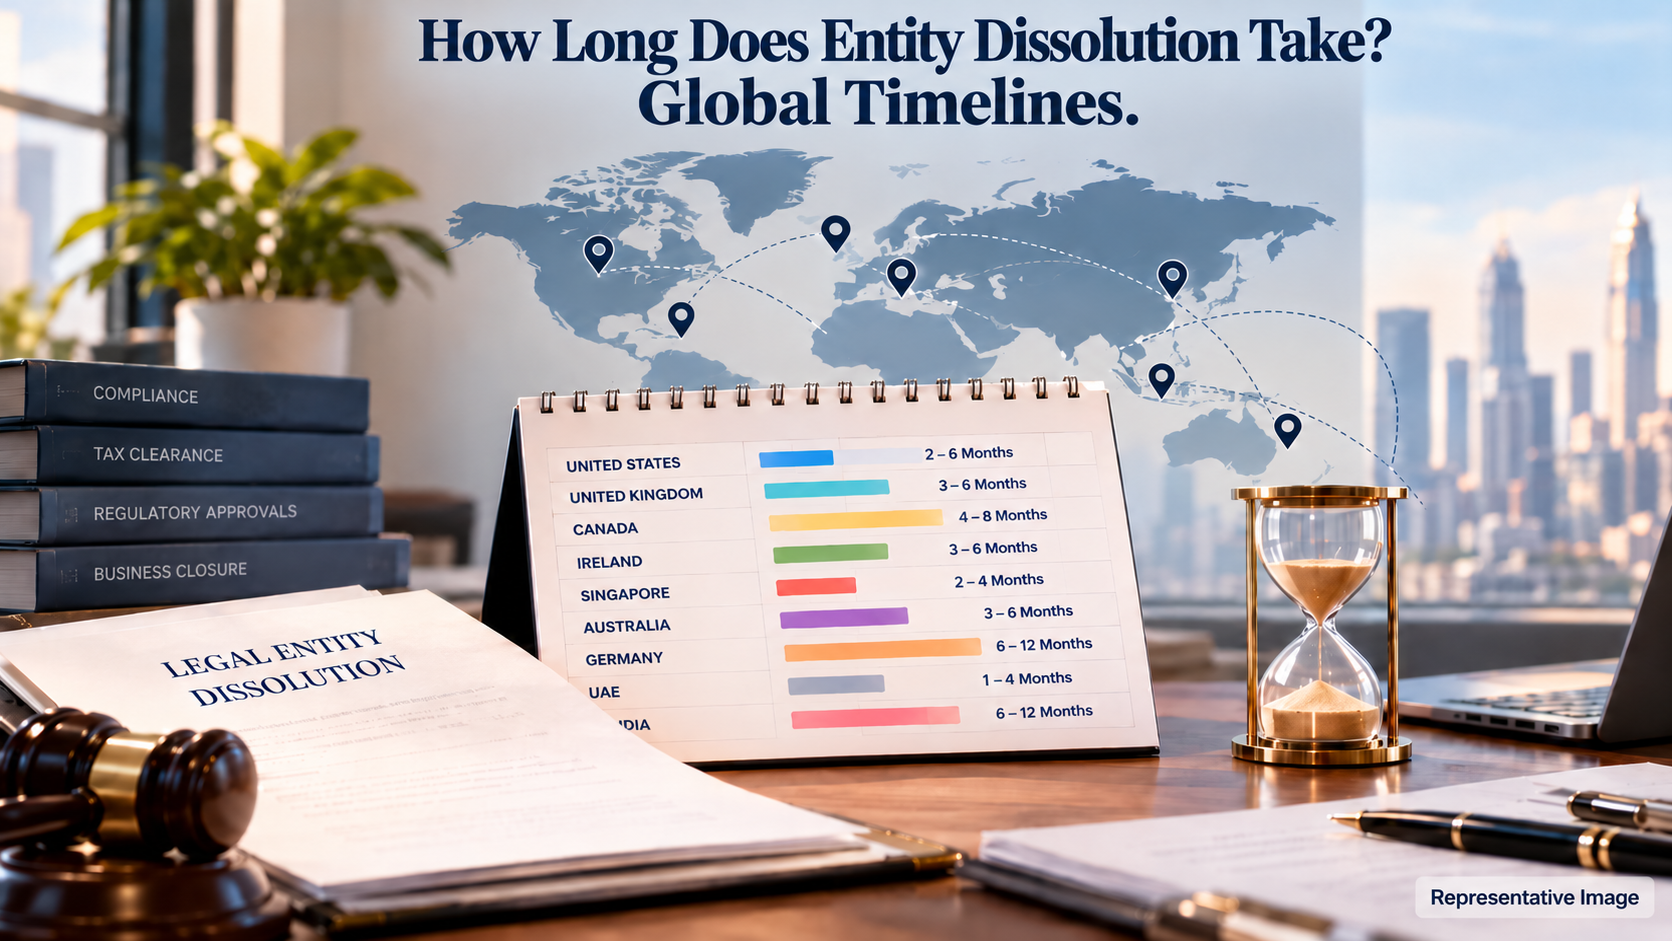
Dissolution Timelines by Jurisdiction
United States (Delaware)
Delaware remains the fastest major jurisdiction for closing a corporate entity. Once outstanding franchise taxes are paid, the Division of Corporations typically processes a Certificate of Cancellation or Certificate of Dissolution in one to three weeks, with same-day and 24-hour expedited options available. Unlike states such as California, Delaware does not require a separate tax clearance certificate before accepting the filing, which removes one of the biggest bottlenecks other states impose.
Singapore
Voluntary strike-off through the Accounting and Corporate Regulatory Authority (ACRA) takes a minimum of three months once the application is approved, and the company is not formally dissolved until that period runs. Before ACRA will accept the application, the Inland Revenue Authority of Singapore (IRAS) must issue tax clearance, which typically takes two to six months depending on the complexity of the company's filings. In practice, a straightforward Singapore exit runs five to nine months end to end; entities with outstanding assessments run longer.
United Kingdom
Voluntary strike-off via Companies House Form DS01 costs as little as £13 for online filing as of February 2026, but cost is not the constraint. After filing, Companies House publishes a notice in the Gazette that opens a two-month window during which creditors, HMRC, or other interested parties can object. A successful objection suspends the process entirely. Companies with assets or liabilities to settle instead go through Members' Voluntary Liquidation, which typically takes approximately one year from the date all required documentation is submitted.
Germany
A GmbH cannot be dissolved on a fast track under any circumstances. German law requires a mandatory one-year waiting period, known as the Sperrjahr, that begins only after the liquidator publishes a formal creditor notice in the Federal Gazette (Bundesanzeiger). No distribution of assets to shareholders is permitted during this window, regardless of how quickly debts are settled. As a result, GmbH liquidation realistically takes a minimum of thirteen months, and often longer once final tax filings and register deletion are factored in.
India
Closing an Indian entity typically takes the longest among major markets, largely because it requires coordinated sign-off across multiple agencies, including the Ministry of Corporate Affairs, income tax authorities, GST, and, where applicable, the Reserve Bank of India under FEMA. Companies managing multi-country wind-downs commonly initiate the Indian process three to six months ahead of comparable jurisdictions to keep exits synchronized.
Other Markets
Timelines across other jurisdictions can vary widely depending on the entity type, local tax clearance requirements, creditor notification periods, regulatory approvals, and whether the company has outstanding assets, liabilities, employees, or statutory filings.
Some markets allow relatively quick administrative strike-offs for dormant or inactive entities, while others require formal liquidation procedures with mandatory waiting periods.
For companies closing operations across multiple countries, these local differences make early planning and jurisdiction-specific compliance checks essential to avoid delays and keep the global wind-down on schedule.
Not sure where your entities fall on this timeline?
Talk to Cerity GlobalWhat Actually Determines the Timeline
The filing itself is rarely what takes time. Four factors do:
- Tax clearance dependencies- Jurisdictions like Singapore and, historically, California will not accept a dissolution filing until the tax authority confirms all returns and assessments are settled. If the tax authority has questions, the clock resets.
- Statutory waiting periods- Germany's Sperrjahr and the UK's two-month Gazette objection window exist by law and cannot be waived by paying a fee or hiring outside counsel. These are fixed, not negotiable.
- Payroll, benefits, and employee offboarding-Entities with local employees carry final payroll runs, statutory severance, and benefits deregistration obligations that must be closed out before the entity itself can close. This is frequently the step companies underestimate most, because it depends on local labor law timelines rather than corporate registry processing.
- Outstanding liabilities and creditor claims-Any unresolved debt, pending litigation, or unfiled return extends the process indefinitely until it is resolved, because most registrars will not finalize dissolution over an open liability.
Why the Process Runs Longer Than Companies Expect
Teams that have only ever incorporated an entity often assume dissolution is incorporation in reverse. It is not.
Incorporation is a single registration event. Dissolution requires proving a negative that no tax is owed, no creditor has a claim, and no employee has an unresolved entitlement across every agency that touched the entity during its life.
Missing a single final filing, such as a last VAT return or a final payroll tax reconciliation, can add months to an otherwise clean exit.
Shortening the Timeline Without Cutting Corners
A few practices consistently compress dissolution timelines:
- Run a pre-dissolution audit of tax filings, payroll obligations, and open contracts before submitting anything to a registrar.
- Initiate tax clearance requests in parallel with, not after, the shareholder resolution to dissolve.
- Close bank accounts and cancel licenses only after final disbursements are confirmed, to avoid reopening the process.
- Sequence multi-country exits so the slowest jurisdiction, typically Germany or India, starts first.
The Cost of Not Dissolving Properly
An entity left in limbo is not a closed chapter. It continues accruing franchise taxes, annual filing obligations, and in some jurisdictions, director liability for missed returns. Companies that abandon an entity rather than formally dissolving it often find that unresolved status blocks future incorporation in the same market or triggers penalties years after operations actually stopped.
Carrying an entity you meant to close months ago?
Check Your Compliance StatusHow Cerity Global Manages Multi-Jurisdiction Exits
Dissolution timelines vary by country, but the coordination problem is the same everywhere: tax, payroll, banking, and legal deregistration all have to close in the right sequence, on schedules set by different local authorities. Cerity Global manages that sequencing across 170+ countries, running parallel workstreams so a global exit does not turn into a series of disconnected local projects.
If you are planning an exit, restructuring a subsidiary, or consolidating a multi-country footprint, talk to our team about a timeline built around your specific jurisdictions, not a generic estimate.
Bottom Line
Entity dissolution timelines are set by statute, not by how quickly you file. Delaware can close in weeks; Germany cannot close in under thirteen months, no matter who you hire.
The real variables companies control are how early they start tax clearance, how clean their final filings are, and whether their exits are sequenced by jurisdiction speed. Get those three right, and dissolution becomes a managed project instead of an open-ended liability.
Frequently Asked Questions (FAQs)
Filing speed can often be expedited for a fee, as in Delaware, but statutory waiting periods like Germany's Sperrjahr or the UK's Gazette objection window cannot be shortened regardless of cost.